Skip to content
Meta

Financial planning for Meta employees

By Vaibhav Goel, registered financial advisor (SEC record) · Formerly at Google, DoorDash and Microsoft

Updated September 30, 2026

I spent fifteen years working in tech before I became a financial advisor, so I know how RSU-heavy pay works and the questions that come with it. This page is the short version of what I’d tell a friend at Meta: the five things I’d do, in order, with a link to the details for each.

Browse Meta guidesPlanning overview

What I’d do with Meta stock and benefits

These five things cover most of what matters. Each one links to a guide with the details.

1. Know when your shares arrive and when you can sell them

Meta RSUs vest quarterly over four years, one-sixteenth at a time, on February 15, May 15, August 15, and November 15, with no one-year cliff. You can only sell during an open trading window, and Meta’s closes at the end of those same months, so you have about two weeks to sell each vest. How Meta RSU grants and vesting work covers the schedule, refreshers, and dividends, and the trading window guide has the dates.

2. Sell most of your RSUs as they vest

I think most people should sell most of their Meta stock as it vests. It’s already been taxed as wages, so selling right away costs almost nothing extra in tax, and holding it is the same as using a cash bonus to buy Meta stock. Selling Meta stock covers how to automate that with a 10b5-1 plan.

3. Raise your tax withholding

Meta withholds 22% for federal tax when your RSUs vest. If your salary and stock put you in the 32% or 35% bracket, that isn’t enough. On $200,000 of RSUs taxed at 35%, the shortfall is $26,000. You can raise the rate to as much as 37% in Workday, which is the easiest fix. How Meta RSUs are taxed walks through the numbers.

4. Get the full 401(k) match, then use the mega backdoor Roth

Meta matches your 401(k) contributions up to $12,250 in 2026, so I’d contribute the full $24,500 if you can. The plan also lets you add up to $35,250 more after-tax and have Fidelity convert it to Roth automatically, but you have to turn on both yourself. The Meta 401(k) guide has the setup steps.

5. Plan ahead for a home, a move, or leaving

If you’re buying a home with Meta stock, work backward from your closing date, because the shares have to vest and the trading window has to be open before you can sell. Buying a home with RSU income covers what lenders count. If you move out of California, the state still taxes part of the RSUs that vest afterward, which the guide to moving states explains. And if you’re leaving, you lose whatever hasn’t vested, so check your vest dates first. Leaving Meta has a checklist.

Do you need a financial advisor?

You might not. If you’re selling your RSUs on a schedule, your withholding is set correctly, the Roth conversion is on, and you’re comfortable managing it yourself, you’re already doing most of what I’d suggest.

Meta also offers financial coaching and tax education as part of your benefits, and I’d start there. It’s worth asking whether it covers your spouse and the accounts you have outside Meta.

Where I think an advisor earns their fee is when several decisions land at once. Maybe you’re buying a house in the same year as a big vest, or you’re sitting on a seven-figure position with a very low cost basis, or you’re moving out of California, or your partner has equity at another company. That’s the kind of work I do.

If you do talk to advisors, including me, ask what you’ll pay in dollars per year and what you get for it. It’s also worth asking how they’d handle the Meta-specific parts, like the withholding gap, the trading window, and the two steps of the mega backdoor Roth.

At Simple Money Advisors, my firm, we manage investments and do ongoing tax planning, and we work with your tax preparer and, when you need one, your attorney. We don’t prepare or file tax returns or draft trusts. Our disclosure brochure explains our services, fees, and conflicts.

Before an introductory call

What should I have ready for a financial planning conversation?

For an intro call, you don’t need anything. Just tell us what you’re trying to decide and any deadline you’re working with. For a detailed review, your RSU award notices, a recent paystub, and a list of your accounts are helpful.

Is Niva Wealth affiliated with Meta?

No. Niva Wealth, which publishes this guide, and Simple Money Advisors LLC, the author's firm, are both independent of Meta. The author worked at Google, DoorDash, and Microsoft.

Meta: company facts

Meta Platforms, Inc. is your employer, the sponsor of the 401(k), and the public company whose stock you receive. The figures below come from Meta’s filings and are as of the dates shown.

$60.8B
Revenue, Q2 2026
Up 28% year over year
75,472
Worldwide employees
June 30, 2026
$20.4B
Share-based compensation, 2025

Quarterly figures are for the quarter ended June 30, 2026. The headcount is for all of Meta worldwide.

Headquarters
Details
Menlo Park, California.
Share classes
Details
Class A shares have one vote and trade on Nasdaq as META. Your RSUs are paid in Class A shares. Class B shares have ten votes and aren’t publicly traded.
Retirement plan
Details
Meta Platforms, Inc 401(k) Plan, plan number 001, sponsor EIN 20-1665019. Fidelity is the trustee and keeps the records.
Meet your financial advisor

Simple Money Advisors LLC is a California state-registered investment adviser.

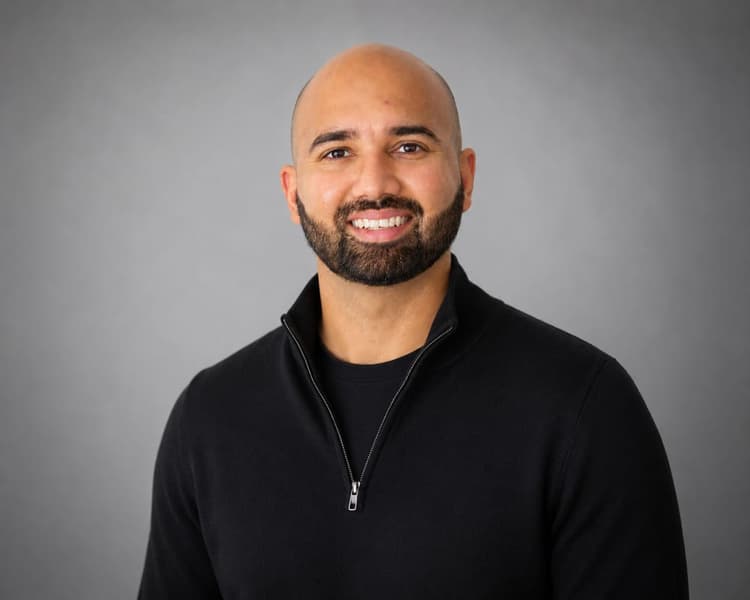
Vaibhav Goel, Registered financial advisor at Simple Money Advisors

Vaibhav Goel

Co-founder of Simple Money · Registered financial advisor · SEC record

Investment adviser representative, registered with the State of California.

Vaibhav spent fifteen years building products at Google, DoorDash and Microsoft before becoming a licensed advisor. He works with people in tech on the whole picture, equity, taxes, investments and cash flow, as one plan rather than four.

Vaibhav Goel on LinkedIn

Talk through your Meta financial planning questions

Book an intro call
Sources & editorial approach

Guide updated September 30, 2026. This guide draws on company filings, government guidance, and independent adviser guides. Each source notes the period it covers, and the examples are illustrations.

  1. [1] Meta: 2025 Form 10-K

    Filed January 29, 2026 for the year ended December 31, 2025. Cover page identity, share classes, dividend and repurchase history, RSU activity and share-based compensation in Note 12, the four-year vesting statement in Note 1, and worldwide headcount in Item 1.

  2. [2] Meta: form of Restricted Stock Unit Award Agreement

    Exhibit 10.2 to the Form 10-Q filed July 31, 2025, under the 2025 Equity Incentive Plan. Sections 1–6 cover settlement, dividend equivalents, transferability, forfeiture and tax withholding; the Jurisdiction-Specific Addendum carries country terms. The applicable individual award and its Notice govern.

  3. [4] Meta: Insider Trading Policy

    Exhibit 19.1 to the Form 10-K filed January 30, 2025, amended September 5, 2024, and incorporated by reference into the 2025 Form 10-K. See Who is covered, Regular Closed Trading Period, Pre-Clearance, Bona Fide Gifts, and Company Incentive Plans. Current internal notices govern individual restrictions.

  4. [7] Meta: Q2 2026 earnings release

    Exhibit 99.1 furnished with the Item 2.02 Form 8-K of July 29, 2026. Unaudited results for the quarter ended June 30, 2026; the employee count is worldwide headcount and includes employees affected by the May 2026 reduction.

  5. [12] IRS Publication 15 (2026): supplemental wages

    Federal payroll withholding methods, including the optional supplemental-wage rate.

  6. [13] IRS Topic 409: capital gains and losses

    Basis, holding periods, and treatment of gains and losses on sale.

  7. [15] IRS: retirement contribution limits for 2026

    Employee deferral and age-based catch-up limits for the 2026 tax year.

  8. [18] California FTB: Publication 1004

    California equity-compensation sourcing, including restricted stock units and changes in residency.

  9. [34] US Department of Labor EFAST2: Meta Platforms, Inc 401(k) Plan, 2025 Form 5500

    Plan year 2025 annual return with audited financial statements for META PLATFORMS, INC 401(K) PLAN (sponsor EIN 20-1665019, plan number 001), received by EFAST2 June 18, 2026. Note 4 describes the plan as operated that year; auditor Ernst & Young LLP, report dated June 15, 2026. The plan document and Summary Plan Description govern.

  10. [40] Meta Careers: benefits

    Official global benefits page, checked September 17, 2026; the page states that program offerings vary based on location. Your current plan documents and eligibility govern.

  11. [47] FAANG FIRE: Meta benefits, RSU details, 401(k) match

    Written by Andre Nader, who worked at Meta for nearly a decade; published October 16, 2024, checked September 30, 2026. First-hand account of quarterly vesting on the 15th of February, May, August and November with no cliff, withholding elections in Workday, automatic in-plan Roth conversions, the match, and a survivor benefit. Secondary reporting, not a Meta document; benefits may have changed since.

  12. [48] Align Financial Solutions: making the most of Meta RSUs

    Independent adviser guide by Hazel Secco, CFP, CDFA, dated January 14, 2026; checked September 30, 2026. Reports the quarterly vest dates, the one-sixteenth schedule and alternatives, and raising RSU withholding in Workday about a week before a vest. Secondary reporting; your Notice governs.

  13. [49] Avier Wealth Advisors: Meta employee benefits

    Independent adviser guide, undated, written against 2025 limits; checked September 30, 2026. Reports quarterly vesting over four years and a federal RSU withholding election between 22% and 37% that must be made a week before the vest. Secondary reporting, not a Meta document.

  14. [50] Safe Landing Financial: Meta mega backdoor Roth guide, 2026 update

    Independent adviser guide by Brian Fry, checked September 30, 2026. Reports after-tax contributions, the automatic in-plan Roth conversion through Fidelity NetBenefits, a 50% match on deferrals and catch-up contributions, and no match on after-tax contributions. Secondary reporting, not a plan document.

  15. [51] TrueWealth Financial Partners: the mega backdoor Roth at Meta

    Independent adviser guide by Glenn Rossman, undated, written against 2026 limits; checked September 30, 2026. Reports after-tax contributions and an automatic in-plan Roth conversion that is added by calling Fidelity. Secondary reporting, not a plan document.

Report a correction

General education for US employees, not personalized investment, tax, or legal advice. Your current award and benefit documents govern your individual terms. Niva Wealth, which publishes this guide, and Simple Money Advisors LLC, the author's firm, are independent of Meta Platforms, Inc. and are not endorsed by it.